Tuesday, July 11, 2006

Classifying investment decisions

I recently read an article by James Montier, who wrote "Behavioral Finance - Insights into Irrational Minds and Markets." He suggested classifying investment mistakes into 4 categories based on two axes:

Good outcomeBad outcome
Right reasonSkillBad luck
Wrong reasonGood luckMistake

Thinking about the decisions that I've recorded here, I can see that all of the individual stock purchases and the single sell have been very good outcomes. In fact all of my positions are beating the S&P 500 index and all but one (Berkshire Hathaway) have annualized returns better than 15%. Looking over the reasons I documented for those decisions, I think I can label my success as mostly skill. I focused on fundamentals and the fundamentals of each company have been good and improving.

The mutual fund investments I've made in my 401(k) had mostly good outcomes. I spent way too much time distrusting active funds (by stayin nearly 100% invested in an index fund) and I picked a poor time to become a bond investor. In the first case, I think I made a mistake by focusing too much on fees. In the second case, I think I've had a bit of bad luck.

But it's a lot harder to evaluate the decisions that haven't resulted in purchases or sells. It's a bit harder to analyze "sins of ommission" at least in part because they don't tend to leave traces in our memory. On the other hand, as Warren Buffett says, there are no called strikes in investing. It's entirely possible I would have made more money by purchasing my half-thought out or rejected ideas. But I'm not sure I would be as comfortable with them.

Wednesday, May 03, 2006

"Revenues are Good, Costs are Bad" and Other Business Myths

Just reading the first myth in "Revenues are Good, Costs are Bad" and Other Business Myths made me think of the struggle Oracle has with the Wall Street analysts who cover it. Oracle has two basic sources of revenue: new licenses and license renewals. New licenses are seen by Wall Street as more desirable since they represent revenue growth. But renewals are much more profitable because Oracle doesn't have to pay a salesman to drum up the bussiness.

Wall Street would also like to see more of Oracle's revenue growth come from its own products rather than from buying competators. But if Oracle can obtain customers more cheaply by buying other bussinesses, it's in the company's interest to do so. The same argument can be made about R&D spending versus buying other company's products.

Tuesday, April 25, 2006

Poorcasting

I just want to lay claim to a word I coined in the middle of the night:

Poorcast
To project that the future will be less prosperous than the present.

Wednesday, April 05, 2006

Bloomberg.com: Canon

So Canon Stock Has Biggest Gain in 2 Years on Digital Camera Sales according to Bloomberg. Not bad. In Tokyo, Canon ended at ¥8,300. $1 = ¥117.38 at the moment, which should mean Canon would trade at $70.67 or so in New York. It actually ended at $71.32, so there seems to be a small "Japan premium" built into the NYSE price. Perhaps that is because the market agrees with Bill Gross that the dollar is headed down—against the Yen in particular.

Naturally, it makes sense to ask if Canon is now overvalued. Quicken's DCF model suggests that the company needs to grow 6.3% over the next 10 years in order to justify its current price when discounted against the S&P 500's long term rate. Even if Canon doesn't expand into new markets, I think 6-7% growth is very likely. And if new products do succeed, 10+% growth should be possible.

Tuesday, April 04, 2006

Investment returns redux

I discovered an error with the spreadsheet I used to generate my investment returns. It turns out I hadn't adjusted the S&P 500 index price for some of my purchases. The effect was to make the Benchmark column wrong:

Stock             Opened  Price  Closed   Price Annualized Benchmark
Oracle           6/24/02   8    5/28/03   13.35     67.05%    -9.94%
Major Automotive 2/28/06   1.75 3/29/06    1.90    144.21%   -11.13% 
Oracle           6/24/02   8     4/4/06   13.84     14.99%     6.80%
Canon            12/9/03  45     4/4/06   68.56     19.04%     2.19%
Canon            12/1/04  49.66  4/4/06   68.56     26.38%     5.34%
Select Comfort    2/9/05  19.95  4/4/06   39.80     80.44%     6.60%
Berkshire (B)    1/31/06   2920  4/4/06    3001      8.29%     2.57%

Now I'm 100% both on absolute and relative terms. Obviously this was a pleasant surprize. Even better, I've been tracking my time-weighted internal rate of return and my IRA is earning about 20% annualized. Since I've held a lot of cash earning less than 4% most of that time, I feel pretty confident in my ability to make good investments over time. If anything, I ought to be making more trades.

Monday, April 03, 2006

Maxco off my watch list

It's sort of sad, but Maxco, Inc. Announces Abandonment of Proposed Transaction to Terminate SEC Registration. This was the first company I started watching for a possible going private arbitrage opportunity. The lesson is to wait for a definitive proxy.

Investment returns

After selling Major Automotive, I started to wonder how well the other positions in my IRA have faired. After cosidering commissions, my two closed positions are:

Stock            Opened   Price Closed   Price Annualized Benchmark
Oracle           6/24/02  8     5/28/03  13.35  67.05%     -9.94%
Major Automotive 2/28/06  1.75  3/29/06  1.90  144.21%    -59.70% 

And here are the open positions assuming commissions, dividends, and today's closing price:

Stock            Opened   Price Closed   Price Annualized Benchmark
Oracle           6/24/02  8     4/3/06   13.79  14.89%      6.68%
Canon            12/9/03  45    4/3/06   67.41  18.20%      2.00%
Canon            12/1/04  49.66 4/3/06   67.41  24.85%     20.25%
Select Comfort   2/9/05   19.95 4/3/06   39.73  80.41%     24.32%
Berkshire (B)    1/31/06  2920  4/3/06   3012   10.78     332.30%

As you can see, all of my investments are currently in the black and I'm 6 of 7 against the S&P 500. Obviously this won't hold up in the future.

Friday, March 31, 2006

SC 13E3 filings

Here are my notes on some recent SC 13E3 filings:

Pegasus Solutions, Inc.
Merger valued at $9.50 a share. Currently trading at $9.39.
Yadkin Valley Company
1-for-50 reverse stock split valued at $78.00. Currently trading at $97.50 a share.
Asconi Corporation
1-for-30 Reverse Stock Split valued at $1 a share. Currently trading at 30 cents a share.
Badger State Ethanol, LLC
Reclassification of Class A member units to Class A-1 member unit for holders of fewer than 20 units. I can't find any trading information on the units.
The Sports Authority, Inc.
Merger valued at $37.25 a share. Currently trading at $36.98.
Foodarama Supermarkets, Inc.
Merger valued at $53 a share. Currently trading at $52.
Masonite International Corporation
Went private in the spring of 2005. I think this is a bug in the SEC's script.
Obsidian Enterprises, Inc.
Went private on March 17. (Timothy S. Durham is also related to this transaction.)
Scheid Vineyards Inc.
1-for-5 Reverse Stock Split valued at $9.25. Currently trading at $6.64.
Stratford American Corporation
Merger valued at $0.80 a share. Currently trading at 78 cents.
Instrumentation Laboratory S.p.A.
Tender offer valued at U.S.$0.98 per ADS. Currently trading at 50 cents.
Lafarge North America Inc.
Tender offer valued at $75.00 per share. Currently trading at $83.86.
Cruzan International, Inc.
Went private on March 22.
Rogers Wireless Communications Inc.
Went private in 2004. Another bug, I think.
William Lyon Homes
Tender offer valued at $93.00. Currently trading at $97.30.
Chiron Corp.
Tender offer valued at $45 a share. Currently trading at $45.70. This is an interesting case. Novartis is trying to by Chiron, which made news recently because it is major supplier of flu vaccine. But it isn't clear how shareholders will vote, since two proxy advisory services covering the deal are split.

These notes cover March 20 to March 30, and as you can see, there aren't any real prospects here. Most of these filings cover tender offers and mergers, which are too competitive. Anyone can make money if they guess the outcome correctly. Yadkin Valley Company is trading (very thinly) above the offer price. Asconi Corporation would be only be worth $29 if someone gave you 29 shares, so the commission would kill me. Scheid Vineyards pays out only $37. So far, I don't see any worthwhile deals.

Thursday, March 30, 2006

Raytheon raises its dividend

Raytheon announced that it is raising the quarterly dividend to 24 cents a share. Last year it was 22 cents and for several years before that it was 20 cents per share per quarter. The new rate pushes the dividend yield over 2% at current prices, which isn't great on its own. But the new trend toward increasing the dividend is very encouraging. One the reasons I feel good about Canon, is that every 6 months management raises the dividend a notch. Giving out cash is not only very good for shareholders, it signals that management is comfortable with the future of the business.

SEC webpage hack

First, I'm using definition 3. a., not 3. b.

Easily the most difficult part of investing in reserve split cashout situations is finding the SEC filing. Companies that intend to "go private" initially file a SC 13E3 ("Going private transaction by certain issuers"). Later they might file a SC 13E3/A (" [Amend]Going private transaction by certain issuers"). Often those filings refer to either a SC TO-T ("Tender offer statement by Third Party") or a PRER14A ("Preliminary Proxy Soliciting materials") which contain the details of the transaction. Normally, companies that are merging or buying out all outstanding shares are less interesting than reverse splits. All of this takes some digging.

Fortunately, the SEC offers an interface to recent filings, but the menu only goes back five business days. But if you change the URL, you can see filings any number of days old. Today's 13E3 filings are: http://sec.gov/cgi-bin/current.pl?q1=0&q2=0&q3=SC+13E3. The ones filed two weeks ago are: http://sec.gov/cgi-bin/current.pl?q1=9&q2=0&q3=SC+13E3.

The next step is to search through the filings for good or potentially good deals. Since the same companies might amend their 13E3 filings dozens of times, it's good to take notes so that you don't duplicate research.

Wednesday, March 29, 2006

Major Automotive transaction completed

I bought Major Automotive on February 28 for $1.75 a share and received $1.90 a share this morning. After accounting for commission (on the purchase), I made $129.90 in 29 days. If I could make this transaction on a continual basis, I'd earn 144% a year.

Of course, the problem is that there aren't enough of these situations and they aren't big enough to constantly do them on a large scale. Which is just as well for me, since if they were, the opportunities would disappear.

Wednesday, March 08, 2006

Major Automotive goes private

I'm one step closer to collecting a quick $128 profit according to this 8-K filing.

Friday, March 03, 2006

USATODAY.com - Oracle? Buy, sell or snooze?

I think Oracle might be undervalued again. As you can guess from the title USATODAY.com - Oracle? Buy, sell or snooze? suggests that Oracle is sleepy stock that isn't worth pursuing. That may be (certainly it has been true for last year or so). Let's go over Matt Krantz's arguments step by step.

"Step 1: Measure the stock's risk and reward."

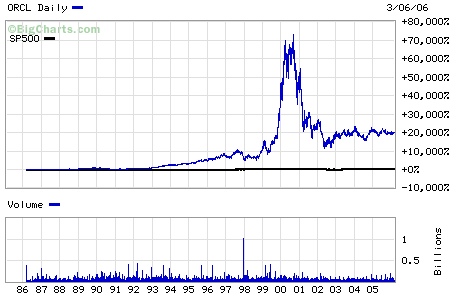
Beta is the measure of how a stock's price moves in comparision with the overall market. According to Oracle's beta, the stock is extremely risky. (It also suggests that Oracle isn't a sleepy stock.) This chart illistrates the risk.

I think most people would be happy with this sort of risk, but it's obvious that if you bought at the wrong time (during 2000) you would have lost a ton of money. On the other hand, if you bought at some of the right times (not during 2000), odds are good you would have come out ok. (I originally bought in 2002, so I'm feeling pretty good about Oracle right now.) If you know how to evaluate Oracle, high beta is actually a plus.

"Step 2: Examine the stock's earnings multiple."

According to the article, Oracle looks pretty good from the P/E ratio standpoint. "But even this should give investors pause, because it shows that Oracle's profitability (defined by return on equity) also has been declining sharply. This is not an encouraging sign." As a matter of fact, since its peak in 2000, ROE has fallen from 97.5% to 26.6%. For comparision, Microsoft's ROE peaked in 1997 at 35.3% and fell to 10.9% for 2004. It's now at 25.5%—a bit less than Oracle. Let's just say, I'm not discouraged.

"Step 3: Calculate the company's value using forecasted future cash flows."

Using the discount cash flow tool at Smartmoney.com I find that is worth somewhere between $11.50 (if you take beta into account) and $13.18. The key assumption is a 12.2% growth rate over the next five years. I think this growth rate is possible, even likely, but I'll talk about why in a moment. Since Oracle is currently priced around $12.80, I'd say it's overpriced if you think beta is a good proxy for risk and fairly priced if you don't.

"Step 4: Check the USA TODAY Stock Meter score."

To be honest, I don't have any idea what this adds to the argument. I tried out a few other stocks to see what their "USA TODAY Stock Meter score" might be, and most companies seem to be in the 3.0 region. I guess I'm not sure what it tries to measure.

So the real question is will the aquistions of PeopleSoft and Siebel provide enough extra earnings to make Oracle's current price a bargain? I think Oracle paid too much for that to happen from cost-cutting alone. As a shareholder, I'm betting that there will be more opportunities for Oracle to sell expensive bundles to companies as a result of these aquisitions. I see Oracle in much the same situation that Microsoft was in around 10 years ago.

Tuesday, February 28, 2006

Why I bought Major Automotive

Today I bought 999 shares of Major Automotive at $1.75 a share. Nearly 100% of the reason may be found in a recent SEC filing. I haven't had many good ideas for long-term investments, so I thought I'd try out an idea for a short-term investment I'd recently read about. The basic idea is to invest in shares that will be cashed out in order for the company to go private.

My hurdle rate for short-term investments is the 4-5% that I will be getting from the money market account my cash will be invested in over the next few months. If I don't expect to earn that rate, I'm better off staying in cash. The Major Automotive proxy says that anyone holding fewer than 1,000 shares will receive $1.90 in cash if the deal is approved. So I stand to receive $1,890.10 for my 999 shares. Including commission ($19.95), I spent $1768.20 to buy my shares, which works out to a $129.90 gain. Obviously, this isn't going to be a huge investment in absolute terms, but it is a little over 7% rate of return.

The one thing I don't know, however, is how long it will be before I get the cash. If the deal is approved at the annual meeting on March 3, and the paperwork takes until the end of the month, I'll be holding the shares for about 1/12 of the year. On an annualized basis, my return (130%) blows away the hurdle rate. Of course, it could take longer than that. But as long as it doesn't become a long-term investment, I'm in good shape.

Monday, February 06, 2006

Why I bought Berkshire Hathaway

Actually the question might be why I didn't buy Berkshire Hathaway earlier. After all Mr. Buffett's annual letters taught me how to value businesses and inspired me to try my hand at investing in individual stocks. The basic insurance business is one of the all-time great business models. Shortly after my wife started her Pampered Chef business, Berkshire bought the company. I've known about GEICO since long before it advertised in earnest. And of course, I'm a big fan of Dairy Queen and See's Candy.

But the strange array of assets that make up the company is a bit hard to value. Thankfully other people are interested in that question as well. A little while ago, I discovered the Berkshire Hathaway Intrinsivaluator. Of course, I've substituted a complicated set of models that I don't completely understand for a business that was complicated, but explained in relatively simple terms by Mr. Buffett. But the nice thing about the models is that we have an objective judgment that extends back through the years.

Currently, the models suggest that the shares are fairly cheap, but not at "cigar butt" level. And going back in time, the intrinsic value for the various models seems to grow by fits and starts. But the price jumps all over the place—far too cheap in 1981, over valued in 1996, and everywhere in between. Lots of times, the market seems to have a handle on the value as calculated by the models.

The real problem with an accurate evaluation, is the nature of the insurance contracts Berkshire writes. Someday there will be one or more super-catastrophes that could threaten the solvency of Berkshire Hathaway if it became undisciplined. In his 2002 letter, Mr. Buffett said, "Had Gen Re remained independent, the World Trade Center attack alone would have threatened the company's existence," in reference to a recently acquired reinsurance subsidiary. But unless and until such a disaster occurs, an insurance company can use the premiums it hasn't yet needed to pay claims (called float) to invest as it sees fit.

In some ways, investing in Berkshire Hathaway is like investing in a large and sucessful mutual fund. On the one hand, the past returns look outstanding. On the other, it becomes harder and harder to find good investments for the cash that keeps rolling in. Unlike a fund manager, Warren Buffett isn't restricted by investment style or SEC restrictions on funds. He may buy whole companies—even privately held companies. And so far, he's managed to get a good return.

Monday, January 09, 2006

The purpose of R&D

The companies I invest in tend to have a high rate of R&D expenses. I suppose some of that is rub-off from where I work. I'd like to have a part in developing cool new technology like fuel cells.

But creating new products is only part of what I look for in a company's R&D. I also would like to see research that makes existing products better and cheaper to manufacture. Not only is it lower risk, it also is harder for other companies to copy. This sort of research can lead to long-term competative advantages.

Why I'm buying the PIMCO Total Return bond fund

For the past year or so, I've been concerned about my original strategy of investing heavily in an S&P 500 index fund. For one thing, I've been investing in active funds that beat their index over the course of several years. Also, it seems like the index is biased toward expensive stocks. I still like the low fees, but I'm concerned that the indexing strategy will be costly if there is a recession—especially since P/E ratios are so high.

Recently, the yield curve inverted slightly. So I decided to move about half my index fund "ballast" into a bond fund.

I only considered funds with expense ratios < 0.5% and manager tenure of 10 years or more. Here are the returns for all candidates in my 401(k) plan:

Investment Name   1 Yr 3 Yr 5 Yr 10 Yr LOF
PIMCO Total Return Inst CL 2.58% 4.89% 6.84% 6.98% 8.54%

PIMCO Total Return is the largest of all bond funds in terms of net assets. For a stock fund, that would be a huge negative, but a bond fund should scale better. Costs are everything in bond funds, since there is little room to differentiate on the basis of picking individual bonds. Unlike stock funds, size doesn't lock bond funds out of the best investments.

Thursday, November 03, 2005

Syntax versus semantics

Recently I had someone contribute some coding changes for my project at work. I had made it clear that I wanted to know all of the things he had changed. He didn't seem willing to do that and for mostly political reasons, I didn't feel I could compel him to give a complete report. So I settled on a compromise: he'd give me a list of "interface" changes.

My idea behind that suggestion was that if he fixed a bug or reformatted some code, I really didn't care too much. But if he changed the way a part of the system operates, I'd like to know the general reasons why. A couple of weeks later, he checked in his code and reported the changes in the interface as he saw it and I started to test the code.

Not surprisingly, something broke. He's an outstanding programmer, but with a large system it isn't easy to make a large number of changes that work right out of the gate in every situation. After digging around for a few hours, I finally discovered the offending code. He had replaced an entire source file with a check-in comment something like, "Replaced with working version." His version changed the semantics of a function call in a way that broke a program in a non-obvious way.

Now, that sort of change is exactly the sort of thing I was fishing for when I asked about "interface" changes. His response was that since the function signature hadn't changed, the interface hadn't changed. And he's correct if we had been talking about syntax. But I don't care about the syntax interface. A compiler can tell me if that changed. I needed to know about semantic changes, which are much more difficult to discover.

Thursday, October 06, 2005

The price of foam

On of the more obscure problems Katrina caused is a shortage of foam used in upholstered furniture. Thankfully, Select Comfort's business model allows them to sell beds now and ship them later, so with careful management it should be possible to avoid lower sales if not fewer deliveries. If the average delivery time goes up only a few days, consumers might not even notice or care.

The principle of supply and demand might cause problems in the long term, however. If foam is in short supply over the next few months, companies that need it will bid up the price in order to ensure they have enough to finish their own products. Until the supply problem is fixed, Select Comfort is at risk of lower profit margins.

Company-specific risks like this are hard to predict unless you have a detailed understanding of the micro-economics of an industry. Even then, the unexpected happens more often the we think. But good companies with solid capital structures and competent management will survive.

Tuesday, October 04, 2005

Capital allocation

The central idea of capitalism is that money is the score-keeper of economic activity. Most people would feel that there are numerous other criteria to judge human endeavors than whether or not it makes money. For instance, artists take pride in creating works that are not commercial, environmentalists oppose companies that pollute, and most people would trade salary for doing what they really enjoy. And if money didn't somehow represent all of those things, capitalism wouldn't work.

Consider labor unions. They demand higher pay and better working conditions for workers at the expense of company profit. Auto workers over the years have virtually guaranteed that US manufacturers will produce more cars than they can profitably sell. In essence the unions have won the battle, since it is Ford, GM and Chrysler who are paying the price, and not the workers. But the war isn't over, and if those companies can't stay in business while paying their wages, all sides will lose.

In other words, money gets converted into what we really value. For organized labor, it gets converted into job security at all costs. Consumers don't particularly care about job security (except their own, of course), but they do care about how much money their car costs. If paying for job security lowers the cost (unlikely) or raises the quality of cars sufficiently, it could be a good use of capital and the companies will thrive.

The problem with the communist systems in Eastern Europe and Russia, was that workers where theoretically valued, but poitical influence was valuable. Over time, the disconnect became unsustainable.